
Cisco — The Company That Built the Network, Then Had to Reinvent What the Network Meant
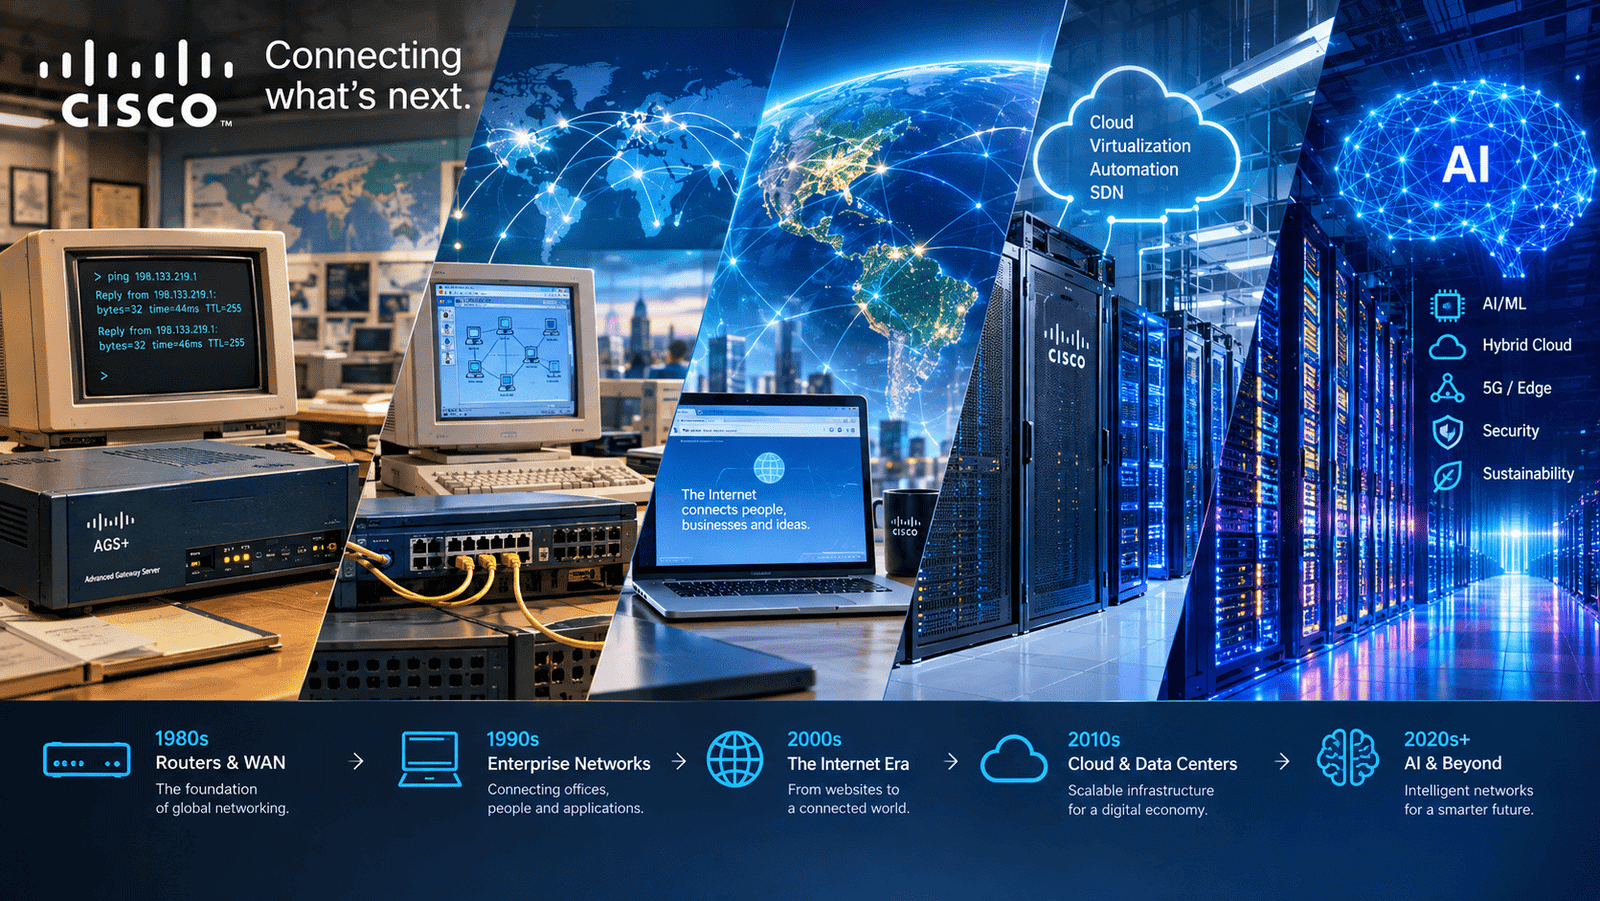
Cisco is one of the rare technology companies whose history is almost inseparable from the history of the internet itself.
The company did not invent the internet. Its importance came from something more consequential for business: Cisco helped build the infrastructure that allowed the internet to expand from a collection of interconnected networks into the backbone of modern computing.
Its routers moved packets between networks. Its switches connected machines inside organizations. Its software controlled increasingly complex infrastructure. Its acquisitions repeatedly extended the company’s reach into wireless, security, voice, video, collaboration and data centers.
At the height of the dot-com boom, Cisco became a symbol of the new economy and briefly stood among the world’s most valuable companies. Then the boom collapsed, demand evaporated and the company confronted one of the most severe inventory and valuation shocks in its history.
Cisco survived.
But survival alone is not the interesting part of its story.
The deeper story is how Cisco repeatedly changed its definition of what a network was.
The first Cisco connected different computer networks.
The next Cisco connected enterprises to the internet.
Then it connected voice, video and data.
Later it tried to connect collaboration, security and cloud infrastructure.
And now it is trying to position the network as the critical infrastructure underneath artificial intelligence.
That makes Cisco a particularly revealing case for understanding technological longevity. Its greatest asset has never been a particular router or switch. It has been its position at a layer that every new generation of computing continues to depend upon: the network.
Cisco Began With a Problem Inside Stanford
Cisco’s origins were remarkably practical.
In 1984, Len Bosack and Sandy Lerner, computer scientists working at Stanford University, were trying to connect different computer networks within the university so that systems using different protocols could communicate. Their work eventually led to the development of a multiprotocol router, and Cisco was incorporated on December 10, 1984.
The problem sounds technical, but the underlying idea was revolutionary.
Computers were becoming increasingly useful, but their value multiplied when they could communicate. A computer that could access information from another computer was more powerful than an isolated machine. A company whose computers could share information was more efficient than one whose departments operated independently.
The network was becoming a new layer of computing.
Cisco positioned itself precisely at that layer.
Its routers did not need to create the information moving through the network. They needed to make sure information could travel from one network to another.
That distinction would become central to Cisco’s business model.
Cisco did not need to own every application.
It needed to become indispensable to the infrastructure carrying them.
The company went public on NASDAQ in 1990.
The timing was extraordinary.
The personal-computer revolution had already created millions of connected machines, but the broader internet revolution was still ahead. Businesses were beginning to build local-area networks, universities were expanding network infrastructure, and the use of TCP/IP was creating the possibility of increasingly interconnected systems.
Cisco was positioned at the intersection.
The Router Became a Platform
During Cisco’s early years, the company’s products were fundamentally about routing.
But routing alone was not enough.
As networks became larger and more complex, customers needed switching, access, security, wireless connectivity and management tools. Cisco increasingly expanded beyond its original category, both organically and through acquisitions.
The company’s acquisition strategy became one of its defining characteristics.
In 1993, Cisco acquired Crescendo Communications, adding switching technology and strengthening its position in workgroup networking. In 1994, it acquired Kalpana, a major Ethernet-switching company. Cisco subsequently added technologies across remote access, ATM, software and other networking categories.
The significance was not simply that Cisco was buying more products.
It was building a broader architecture.
A customer could increasingly buy multiple layers of its network from one company.
That created a powerful commercial advantage. Once Cisco became deeply embedded in a customer’s infrastructure, replacing it was no longer a matter of swapping one product for another. It could mean redesigning an entire network.
Cisco’s own management recognized this tension between scale and entrepreneurial speed. In 1995, the company reorganized around business units so that it could combine the resources of a large corporation with the speed of smaller technology companies.
That organizational model became particularly important because Cisco was about to enter the fastest growth phase of its history.
John Chambers Arrived at Exactly the Right Moment
John Chambers became Cisco’s president and CEO in 1995.
His tenure would last more than two decades and become closely associated with Cisco’s expansion from a networking specialist into a broad technology infrastructure company.
Chambers understood that the market Cisco was serving was much larger than the market for routers.
The internet was changing the architecture of business.
Companies were connecting offices.
Employees were communicating across networks.
Customers were beginning to interact with businesses digitally.
Data was moving between organizations.
And telecommunications companies were rebuilding infrastructure around packet-based networking.
Cisco’s opportunity was to become a supplier to all of these transitions.
The numbers began to reflect the scale of the opportunity.
In the first quarter of fiscal 1996, Cisco’s sales reached $710.2 million, up 81% from the comparable period a year earlier.
Cisco was no longer a small specialist.
It was becoming one of the central suppliers of the emerging internet economy.
The Internet Turned Cisco Into Infrastructure
The late 1990s were extraordinary.
The web transformed the internet from a technology primarily used by specialists and institutions into a mass commercial platform. Businesses suddenly needed websites, internet connections, corporate networks, remote access and increasing amounts of bandwidth.
Every new internet service created demand somewhere inside the network.
And Cisco was positioned near the center of that spending.
The company expanded aggressively.
It acquired companies involved in switching, wireless, optical networking, voice, security, access and other emerging technologies. Cisco’s acquisition records show an extraordinary pace of expansion during the late 1990s, including Aironet in wireless networking and multiple companies in optical transport and internet infrastructure.
The strategy was clear.
If the internet was turning into the world’s communications infrastructure, Cisco wanted to supply as much of that infrastructure as possible.
In 2000, Cisco described its strategic vision as the “Network of Networks.” Chambers argued that the internet was creating a fundamental economic transition and that Cisco’s expertise could allow businesses, telecommunications companies and enterprises to adapt to it.
The language was ambitious because the opportunity was enormous.
For a moment, Cisco appeared almost synonymous with the internet economy.
The Peak Was Extraordinary — And So Was the Fall
Cisco’s rise became one of the defining stories of the dot-com era.
But the company’s extraordinary valuation was not simply the result of irrational speculation detached from a real business.
There was a genuine structural revolution happening.
The problem was that the market began pricing future network demand as though the growth curve would continue almost without interruption.
It did not.
The dot-com bubble burst.
Telecommunications companies and internet startups that had been buying enormous amounts of infrastructure suddenly cut spending. Some disappeared entirely. Others were left with excess capacity and equipment.
Cisco discovered that the network could be strategically indispensable while still being subject to brutal capital-spending cycles.
Its fiscal 2001 annual report described the year as the most difficult in the company’s history. Cisco said that the first part of the fiscal year had begun with revenue growth above 60%, but that the second half became extremely challenging. The company had grown from a startup into a business with more than $22 billion in revenue in roughly a decade.
The reversal was not merely a stock-market event.
It entered Cisco’s operations.
Customers delayed purchases.
Orders were cancelled.
Inventory accumulated.
Cisco had to write down large amounts of inventory as demand deteriorated.
The company that had become famous for predicting the growth of the internet suddenly had to deal with the consequences of having built for a future that had arrived too quickly and then temporarily stopped.
This is one of the most important moments in Cisco’s history because it exposes a vulnerability that is easy to miss when looking only at the company’s long-term success.
Infrastructure companies do not merely depend on technological adoption. They depend on the spending cycles created by that adoption.
The internet could continue growing while Cisco’s customers temporarily stopped buying equipment.
That distinction would shape the company for decades.
Cisco Survived by Becoming More Than a Router Company
The post-bubble Cisco could not simply wait for networking demand to recover.
It had to broaden the business.
The company’s acquisition strategy continued, but the logic became increasingly expansive.
Cisco moved into wireless networking, security, voice over IP, storage networking, video, home networking and other adjacent categories.
The 2003 acquisition of Linksys expanded Cisco into consumer and small-business networking.
In 2005, Cisco agreed to acquire Scientific-Atlanta for approximately $6.9 billion, adding set-top boxes and video distribution technologies and extending the company’s ambitions toward the digital home and carrier networks.
These moves reveal a recurring Cisco pattern.
When a technology transition threatened to commoditize the company’s existing market, Cisco tried to move one layer outward.
Networking became communications.
Communications became collaboration.
Connectivity became security.
Infrastructure became services.
The company was repeatedly trying to ensure that the network remained the center of the architecture.
Cisco’s Great Challenge Was Not the Internet — It Was What Came After
The internet revolution did not end when websites became ubiquitous.
It evolved.
Computing moved into data centers.
Cloud computing became dominant.
Virtualization changed how infrastructure was deployed.
Mobile devices exploded.
Software became increasingly important.
Public-cloud providers such as Amazon Web Services began operating enormous computing environments, changing the economics and architecture of enterprise IT.
Cisco remained a critical infrastructure supplier, but the center of gravity of technology was shifting.
The company could no longer assume that the enterprise would buy networking equipment according to the same architecture that had defined the previous generation.
This created a strategic tension.
Cisco’s historical strength was its control over networking infrastructure.
But the technology industry was increasingly organized around software, cloud services and hyperscale data centers.
Cisco therefore began pushing harder into software, security and recurring revenue.
Its Webex collaboration business, security products and broader software portfolio were attempts to move Cisco beyond hardware.
The direction was correct, but the transition was not instantaneous.
The Company Had to Learn to Live Without Chambers
John Chambers stepped down as CEO in 2015, after more than two decades at the helm.
Chuck Robbins succeeded him.
The leadership transition represented more than a change in personality.
Chambers had been the architect of Cisco’s expansion during the internet era. Robbins inherited a company that needed to operate in a world where networking was still essential but no longer sufficient as the primary strategic narrative.
Cisco needed software.
It needed security.
It needed cloud connectivity.
It needed recurring revenue.
And it needed to compete in markets where companies could innovate much faster than the traditional networking industry.
Under Robbins, Cisco continued an aggressive acquisition strategy.
The company bought AppDynamics in 2017, Duo Security in 2018, ThousandEyes in 2020 and other businesses aimed at strengthening software, observability and security capabilities.
The strategic direction was increasingly clear:
Cisco wanted to understand not only how data moved, but what was happening to the systems, applications and users connected through that data.
That distinction would eventually become crucial.
Security Became Part of the Network
The modern enterprise network is fundamentally different from the network Cisco helped build in the 1990s.
Employees work from home.
Applications run in multiple clouds.
Devices connect from almost anywhere.
Customers interact through web and mobile applications.
Data crosses organizational boundaries.
The perimeter that once separated a company from the outside world has become far less meaningful.
That makes networking and security increasingly interconnected.
Cisco began moving toward a platform model in which networking, security and visibility could be integrated rather than purchased as isolated products.
This was also where observability became strategically important.
If the network is the nervous system of digital infrastructure, observability is part of the mechanism that tells an organization what the nervous system is experiencing.
Cisco’s acquisition of ThousandEyes strengthened this capability.
But the most consequential move came later.
Splunk Was Cisco’s Biggest Bet on the Software Layer
In 2023, Cisco announced its agreement to acquire Splunk for approximately $28 billion, making it one of the largest acquisitions in the company’s history.
The transaction closed on March 18, 2024, with Cisco paying $157 per Splunk share in cash and recording approximately $27.1 billion in purchase consideration.
Splunk was fundamentally different from the companies Cisco had historically acquired.
It was not primarily about moving packets.
It was about data.
Splunk’s technologies provided analytics, security information and event management, observability and tools for understanding enormous quantities of machine-generated data.
Cisco was therefore acquiring something that complemented its historical position.
The network produces information.
Splunk helps interpret information.
The combination allowed Cisco to make a broader proposition: connect the infrastructure, protect it and understand what is happening across it.
This was Cisco attempting to move further up the value chain.
The router had been the beginning.
The data generated by the router could become part of the next business.
AI Changed the Meaning of Cisco’s Original Business
Then artificial intelligence arrived as the next enormous infrastructure cycle.
At first glance, AI might appear to threaten Cisco.
The most visible components of AI infrastructure are GPUs, accelerators and enormous computing clusters. Companies such as NVIDIA became central to the AI hardware story.
But AI has an infrastructure requirement that is easy to overlook.
The machines have to communicate.
Training enormous models requires enormous amounts of data to move between computing resources. Inference at scale requires connectivity between servers, storage, users and applications.
As AI clusters become larger, networking becomes more important, not less.
This puts Cisco back near a technological transition that resembles the environment in which it originally thrived.
The difference is scale.
The networks connecting AI infrastructure can require extremely high bandwidth, low latency and sophisticated management.
Cisco has responded with its Silicon One architecture and networking systems designed for large-scale AI infrastructure.
The strategy is not to compete directly with every component of the AI computing stack.
It is to own a critical layer beneath it.
That is almost exactly the strategy that made Cisco powerful during the original internet expansion.
The Numbers Suggest the New Curve Has Already Begun
Cisco’s fiscal 2026 results provide an important update to the story.
Revenue reached $63.3 billion, up 12% from fiscal 2025. Product revenue increased 16%, while networking product revenue rose 22% to $34.7 billion. Cisco attributed much of that networking growth to AI infrastructure, including systems based on Silicon One and optical technologies.
AI infrastructure from hyperscale customers represented approximately 6% of Cisco’s total revenue in fiscal 2026, compared with less than 2% in fiscal 2025.
That is significant.
Cisco is not merely talking about AI as a future opportunity.
AI infrastructure has already become visible in its financial results.
The company’s networking business, which many observers might associate with an older phase of technology, was one of the areas benefiting most directly from the new AI spending cycle.
That is the paradox at the center of Cisco’s history.
The technology changes.
The network remains.
Cisco Is Becoming a Different Kind of Infrastructure Company
Cisco’s current portfolio is much broader than the company of the 1980s or 1990s.
Its business is now organized around networking, security, collaboration and observability, with software and services increasingly intertwined with those categories.
In fiscal 2026, Cisco generated:
- $63.3 billion in total revenue
- $34.7 billion from networking products
- $8.2 billion from security
- $4.3 billion from collaboration
- $1.1 billion from observability
- $15.0 billion from services
The company is therefore no longer simply selling routers and switches.
It is selling an increasingly integrated infrastructure stack.
That matters because the economics of infrastructure are changing.
Hardware alone tends to face pricing pressure and product cycles.
Software, subscriptions, security and observability can produce deeper customer relationships and recurring revenue.
Cisco’s fiscal 2025 subscription revenue had already reached $31.5 billion, or 56% of total revenue.
The company that once depended heavily on hardware sales has been gradually converting itself into a hybrid infrastructure-and-software business.
The Real Cisco Curve
Cisco’s history can be divided into several strategic centers.
First came routing.
Cisco solved the problem of connecting different networks.
Then came internetworking.
The company expanded from routers into switching, access and broader enterprise networking.
Then came the internet boom.
Cisco became one of the defining infrastructure companies of the web economy.
Then came the crash.
The collapse of the dot-com bubble exposed the cyclicality and capital intensity of Cisco’s customers.
Then came diversification.
Wireless, security, voice, video, collaboration and other technologies broadened the company’s addressable market.
Then came the cloud era.
Cisco had to move from a hardware-centered identity toward software, services and recurring revenue.
Then came security and observability.
The network became inseparable from the security and operational visibility of the systems running on top of it.
Now comes AI.
Cisco is betting that the explosive growth of AI computing will require an equally significant expansion of networking infrastructure.
The company has therefore spent more than four decades moving along the same fundamental curve:
connect → scale → secure → observe → compute.
Its products changed because the meaning of connectivity changed.
Cisco’s Greatest Advantage Is Also Its Greatest Constraint
Cisco’s installed base is enormous.
Enterprises, governments, telecommunications companies and other organizations have built infrastructure around its technology for decades.
That creates trust, distribution and switching costs.
But it also creates a risk.
A company that becomes synonymous with an existing architecture can become too closely associated with that architecture.
Cisco experienced this tension when computing moved from traditional enterprise infrastructure toward cloud-native environments.
Its survival required accepting that the network was no longer the complete product.
The network was the foundation.
Security sat on it.
Applications moved through it.
Data accumulated around it.
Users depended upon it.
And now AI computation depends upon it.
Cisco’s future therefore depends on continuing to move upward without abandoning the layer that made it powerful.
The Company That Survived the Internet Bubble Is Now Betting on the Next Internet
There is an irony in Cisco’s story.
During the dot-com boom, the company was valued as though the internet would transform every part of the economy.
The market was directionally right about the transformation and disastrously wrong about the speed and economics of the transition.
Cisco experienced the consequences.
Yet the underlying thesis eventually became reality.
The world did become dependent on networks.
The internet did become infrastructure.
Digital communication did become central to nearly every industry.
And Cisco remained there.
Now the company faces another technological wave.
AI is creating new computing architectures, new data flows and new requirements for connectivity.
Cisco is betting that the network will again become one of the least visible but most important components of a technological revolution.
That is a much more defensible thesis than simply saying that Cisco is an “old networking company benefiting from AI.”
Cisco’s history shows why.
The company’s most important innovation was never a particular router.
It was recognizing that when computing changes, the network beneath computing changes with it.
That insight allowed Cisco to survive the transition from isolated computers to the internet, from the internet to cloud computing, and now from cloud computing toward AI infrastructure.
The next challenge is whether Cisco can remain fast enough while operating at the scale of an infrastructure incumbent.
Its history gives it an extraordinary advantage.
It has already survived the moment when the future looked obvious.
The harder task now is making sure that the future does not become obvious to everyone else before Cisco has built the next layer.
A CURVE IN 60 SECONDS
1984 — Len Bosack and Sandy Lerner found Cisco in Silicon Valley after developing technology for connecting different computer networks.
1990 — Cisco goes public on NASDAQ.
1993 — Acquisition of Crescendo strengthens Cisco’s switching capabilities.
1994 — Acquisition of Kalpana expands Ethernet switching.
1995 — John Chambers becomes the central leader of Cisco’s expansion.
1995–1999 — Cisco rapidly expands through acquisitions into switching, access, software, wireless, optical networking and other technologies.
2000 — Cisco promotes its “Network of Networks” vision as the internet transforms communications and business.
2001 — The dot-com and telecom collapse produces Cisco’s most difficult period to that point; the company reports more than $22 billion in revenue but faces a dramatic deterioration in demand.
2003–2005 — Linksys and Scientific-Atlanta expand Cisco into consumer networking, video and the digital home.
2015 — Chuck Robbins succeeds John Chambers as CEO.
2017–2020 — Cisco accelerates expansion into applications, security and observability through acquisitions including AppDynamics, Duo Security and ThousandEyes.
2023 — Cisco announces its acquisition of Splunk for approximately $28 billion.
2024 — Splunk acquisition closes for approximately $27 billion in merger consideration.
2025 — Cisco generates $56.7 billion in revenue; subscriptions account for 56% of revenue.
2026 — Revenue reaches $63.3 billion, networking revenue grows 22%, and AI infrastructure becomes a visible driver of Cisco’s growth.
THE POSTMORTEM
What created Cisco’s growth?
Cisco occupied a critical layer of the emerging internet architecture. As businesses and telecommunications companies connected more systems, demand for routing, switching and network infrastructure expanded rapidly.
What sustained its dominance?
The company built a broad portfolio around the network and used acquisitions to enter adjacent categories. Its installed base, enterprise relationships, channel ecosystem and technical integration created substantial switching costs.
Where did the vulnerability emerge?
Cisco became highly exposed to the capital-spending cycles of telecommunications companies, enterprises and internet businesses. The dot-com collapse demonstrated that even an indispensable infrastructure supplier could experience severe financial pressure when customers stopped spending.
What changed the trajectory?
Cisco diversified beyond routing into switching, wireless, security, voice, video, collaboration, software and observability. The acquisition of Splunk represented an especially important move toward data, security and software.
What was internal versus external?
Cisco controlled its product architecture, acquisition strategy and organizational evolution. It did not control the dot-com crash, the shift toward cloud computing, the emergence of software-defined infrastructure or the arrival of generative AI.
What remains uncertain?
The central question is whether Cisco can convert the AI infrastructure boom into a durable new strategic center rather than another temporary hardware cycle. Its fiscal 2026 results provide strong evidence that AI is already contributing materially to networking demand, but the durability of that cycle remains the key question.
LESSONS FROM THE CURVE
1. Infrastructure companies can outlive technological eras when they own the layer beneath them.
Cisco survived because computing repeatedly became more dependent on networking rather than less.
2. A technological monopoly is never permanent.
Cisco’s dominance in networking did not eliminate the need to reinvent the portfolio as cloud computing, software and security changed the architecture.
3. Acquisitions are most powerful when they reinforce the strategic center.
Cisco repeatedly bought technologies that expanded its position around the network rather than abandoning the network altogether.
4. Growth can create operational vulnerability.
The dot-com collapse demonstrated that infrastructure demand can disappear faster than installed capacity can be adjusted.
5. Hardware companies need software when infrastructure becomes intelligent.
Cisco’s movement into security, observability, analytics and subscriptions reflects the increasing importance of software in managing physical infrastructure.
6. The next technological revolution often increases demand for an old layer.
AI may make networking more important precisely because AI requires enormous amounts of computing resources to communicate.
7. The most valuable position is often the least visible one.
Most users never think about Cisco when they open an application or send data across the internet. Yet the infrastructure underneath those actions can be indispensable.
FAQ
What did Cisco originally make?
Cisco began with networking technology, particularly multiprotocol routers designed to allow different computer networks to communicate.
Why did Cisco become so important during the internet boom?
The rapid expansion of the internet created enormous demand for routers, switches and other networking infrastructure. Cisco became one of the central suppliers of that infrastructure.
Did Cisco collapse when the dot-com bubble burst?
No. Cisco suffered a severe downturn, including major inventory and demand problems, but survived and continued expanding into adjacent technologies.
Why was the dot-com crash so damaging to Cisco?
Cisco’s customers — especially telecommunications companies, internet businesses and other network-intensive organizations — had dramatically increased capital spending during the boom. When the market collapsed, they cut orders and reduced infrastructure investment, creating a sharp mismatch between Cisco’s inventory and actual demand.
Why did Cisco buy Splunk?
Splunk strengthened Cisco’s position in security, observability and data analytics. The combination allows Cisco to connect its network infrastructure with broader visibility into what is happening across an organization’s digital environment.
Is AI really important to Cisco’s current business?
Yes. In fiscal 2026, Cisco’s networking product revenue increased 22%, primarily driven by AI infrastructure solutions, and AI infrastructure represented approximately 6% of total company revenue, compared with less than 2% in fiscal 2025.
SOURCES
- Cisco — 2026 Form 10-K and financial results. (Comissão de Valores Mobiliários)
- Cisco — 2025 Annual Report. (Cisco)
- Cisco — Company history and 25th-anniversary history. (Notícias Cisco)
- Cisco — Historical acquisition records. (Cisco)
- Cisco — Crescendo acquisition. (Notícias Cisco)
- Cisco — Kalpana acquisition. (Notícias Cisco)
- Cisco — Scientific-Atlanta acquisition. (Notícias Cisco)
- Cisco — “Network of Networks” strategy. (Notícias Cisco)
- Cisco — Splunk acquisition. (Cisco Investidores)
- U.S. SEC — Cisco fiscal 2026 Form 10-K. (Comissão de Valores Mobiliários)